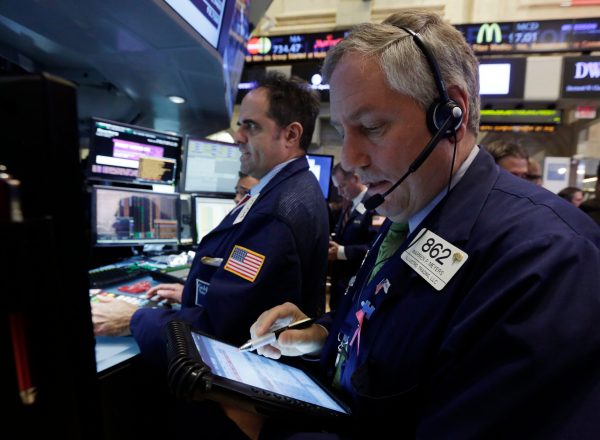
Companies with the most debt and lowest returns on assets are turning the biggest six-week rally in stocks since 1938 into a bloodbath for last year’s best- performing trading strategy.
Investors using so-called quantitative momentum strategies — which speculate that the worst stocks in the past 12 months will continue to decline — have become this year’s biggest losers after banks and companies that rely on consumer spending surged. Quant momentum techniques may have lost 27 percent this month in the U.S., the most since at least 1993, while those in Europe may have dropped 20 percent in March and 24 percent in April, according to data compiled by JPMorgan Chase & Co.
Recommended Stories
Print subscriber? Click here to login/register your account
Digital subscriber? Click here to login/register your account.