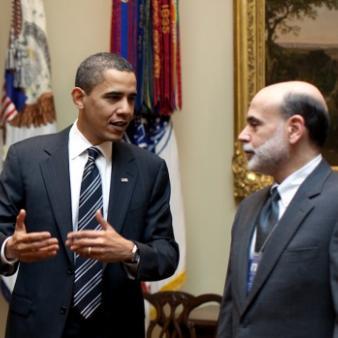
LIKE THE CAVALRY coming over the hill just as the Indians were about to overwhelm the wagon train, Ben Bernanke rode to the rescue of beleaguered investors. He opened the discount window, making it possible for those desperate for liquidity to show up, hand over some assets that no one seems willing to buy, and borrow cash against those assets. The Fed specifically listed “home mortgages and related assets” as acceptable collateral.
Bernanke once said that the way to end a liquidity problem is to hop into a helicopter, and shower the country with cash, leading to the nickname “Helicopter Ben.” Fortunately, he knows the difference between a professor’s joke and a Fed chairman’s policy. He knows, too, that he cannot bail out imprudent lenders and borrowers without creating moral hazard–encouraging a repeat of such behavior. So he has made it possible for banks and other institutions to get their hands on sufficient cash to give them time to work out their problems, but only by paying interest rates that are higher than those routinely charged overnight borrowers. Walter Bagehot must be smiling from on high, as his prescription is applied to ailing markets, “Lend freely against good collateral at a penalty rate.”