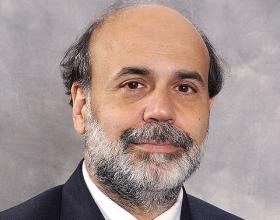
Here is an easy way for any non-economist to tell whether an economy is in dire straits: If investors are looking to their central bankers to get them out of the mess created by over-borrowing, ineffective regulation, and political paralysis. Markets unwilling to lend money at reasonable rates? No problem. Federal Reserve Board chairman Ben Bernanke, Bank of England governor Sir Mervyn King, and European Central Bank president Mario Draghi will drive interest rates down. Banks with near-worthless assets included on their balance sheets as if they could be sold at face value? No problem. Your central banker will go along with the fiction. Mortgage rates too high to get the housing sector back to health? Don’t worry, be happy. Your central banker will try to offset banks’ tighter credit standards by buying up mortgages to keep rates down.
Of course, if you are a saver rather than an over-borrowed consumer, you should not be happy, and should worry, because your savings and pension accounts will earn interest rates so low that inflation will push them into negative territory. And if your range of vision takes you beyond the next day’s share trading, you might worry that some of that money being printed might end up in the bushel basket in which you will tote it to the grocer. Well, not quite: such visions of history repeating itself are still confined to Germany—and, of late, Argentina. But you are entitled to view with more than a little skepticism central bankers’ claims that if they see the inflation genie gaining strength, they will know how to keep it in its bottle. In Paper Promises, Philip Coggan notes in his detailed survey of the history of monetary policy, “Paper money systems have always led to rapid inflation in the past.”
Stay informed.Stay ahead.
Join Washington Examiner for unlimited access to the news, analysis, and commentary that matter most.
Already a member? Log in